
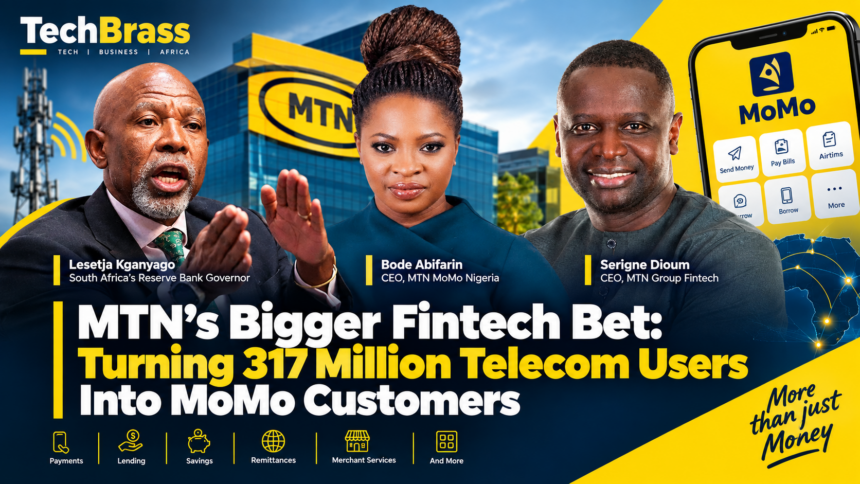
MTN is betting on a much bigger future for MoMo, with the telecom giant looking to turn more of its 317 million subscribers into active MTN MoMo customers across payments, lending, savings, remittances and digital services.
The strategy goes beyond getting people to send and receive money.
They wants MTN MoMo customers to use the platform as a broader financial and digital hub — a place to make payments, save money, access loans, receive international transfers, pay merchants and use everyday digital services.
At the centre of that strategy is Serigne Dioum, CEO of MTN Group Fintech, who sees an opportunity to move MoMo from a mobile money service into a much larger digital financial ecosystem.
MTN’s latest figures show the scale of the opportunity. As of June 2026, the group had 317.7 million customers across 19 markets, while MoMo had 70.8 million monthly active users. MTN also reported 13 billion fintech transactions worth about $330.5 billion in the first half of 2026.
The gap between those numbers is where MTN sees its next major growth opportunity.
MTN Wants More Than Mobile Money Customers
MoMo started as a convenient way for customers to move money using their mobile phones.
That business has grown considerably.
Today, MTN’s fintech platform supports payments, e-commerce, lending, remittances and other digital financial services. MTN says its MoMo platform had 70.8 million monthly active users in the first half of 2026, alongside 2.3 million active merchants and 1.4 million active agents.
But MTN’s larger ambition is to increase the number of telecom customers who become active MTN MoMo customers.
The thinking is simple:
A customer who already uses MTN for connectivity is already inside the company’s ecosystem.
The next step is convincing that customer to use MoMo for more parts of everyday life.
That could mean:
- Sending and receiving money
- Paying merchants
- Saving
- Accessing loans
- Receiving remittances
- Paying bills
- Buying digital services
- Supporting a small business
- Accessing other financial products
The more services customers use, the deeper their relationship with MoMo becomes.
The 317 Million Subscriber Opportunity
Yellos 317.7 million subscriber base is the company’s biggest potential distribution advantage.
But those subscribers are not automatically MoMo customers.
This distinction matters.
therefore does not simply need to acquire more telecom subscribers. It needs to convert existing customers into active financial-service users.
That makes customer engagement one of the biggest priorities for the fintech business.
Yello itself describes its broader fintech ambition as a move from mobile financial services toward mobile financial platforms, covering areas such as wallets, payments, remittances, micro-loans and other digital financial services.
For TechBrass, this is where the story becomes bigger than MTN.
It reflects a wider African technology trend: telecom companies are increasingly using their massive distribution networks to enter financial services.
Nigeria Could Be One of MTN’s Biggest Tests
Nigeria is one of the most important markets in this strategy.
MTN has already strengthened its MoMo operations in the country and appointed Bode Abifarin as CEO of MoMo Payment Service Bank Nigeria.
The objective is to expand the platform’s financial capabilities while creating closer connections between MTN’s telecommunications and fintech businesses.
For Yello, Nigeria offers a combination of scale, mobile adoption and significant demand for digital financial services.
The opportunity is not simply to sign up new users.
It is to turn existing MTN customers into active MTN MoMo customers.
That means increasing the number of services customers use and how frequently they return to the platform.
South Africa Presents a Different Challenge
South Africa is a different market.
The country already has a highly developed banking system and sophisticated financial infrastructure.
That means MTN cannot rely solely on financial inclusion as its selling point.
Instead, the opportunity could come from convenience, merchant payments, lending and new digital services.
Changes in South Africa’s national payments infrastructure could also create new opportunities for fintech companies.
For MTN, the goal is to use its existing customer relationships and distribution network to participate in that evolving financial ecosystem.
MoMo Is Already Moving Into Lending
Payments are only one part of MTN’s fintech strategy.
Lending is becoming increasingly important.
Yello says its fintech operations are already facilitating significant lending activity, while Dioum has argued that a large portion of Africa’s potential lending demand remains underserved.
This creates an opportunity for MoMo to move customers through a broader financial journey.
A customer could begin with a wallet.
Then come savings.
Then payments.
Then credit.
Then working capital.
For small businesses, the relationship could eventually extend into financing and other business services.
That creates a much deeper relationship than a customer who only uses MoMo occasionally to transfer money.
Why Ant International Matters
Yello’s partnership with Ant International is another important part of the strategy.
The partnership is designed to help transform MoMo into a broader digital ecosystem, including a mini-app platform that can connect consumers and merchants with additional digital, financial and commerce services. MTN announced the partnership in June 2026 and said the initiative is expected to launch in Nigeria.
This could help MTN move closer to the super-app model.
Instead of trying to build every service itself, MTN can create a platform where partners integrate their own products and services.
That could make MoMo more useful to customers while giving businesses another route to reach millions of potential consumers.
For MTN, the objective is no longer just to own the payment. It is to own more of the ecosystem around the payment.
Payment Could Become the Last Step
This is one of the most important ideas behind MTN’s strategy.
Traditionally, mobile money begins with payment.
Yello’s longer-term vision is different.
Payment becomes the final action after the customer has already entered the ecosystem to perform another activity.
A customer could open MoMo to:
Save → Borrow → Shop → Pay
Or:
Receive money → Transfer → Purchase → Pay
Or:
Access working capital → Buy inventory → Sell → Receive payment
In that model, payment is no longer the entire product.
It becomes part of a much larger digital experience.
Smartphones Could Change the MoMo Experience
USSD has played an important role in mobile money adoption across Africa.
But smartphone adoption gives MTN another opportunity.
A smartphone app can provide a much richer environment for customers than a basic USSD menu.
It can combine payments, lending, savings, merchant services, remittances and other digital products in one interface.
That could help MTN move customers from occasional transactions to regular platform engagement.
The ultimate goal is to make MoMo something customers return to because it is useful — not simply because they need to transfer money.
Regulators Will Be Critical
MTN’s fintech ambitions also depend heavily on regulation.
The company operates across multiple African markets, each with its own rules covering payments, electronic money, lending and financial institutions.
That means MTN cannot simply deploy one identical fintech model everywhere.
Instead, the company has to work within each market’s regulatory framework.
Dioum has also argued for closer collaboration between fintech companies and regulators, including the use of regulatory sandboxes to test new products before they are introduced more broadly.
That relationship will become increasingly important as MoMo expands from payments into lending, digital commerce and other financial services.
What MTN Is Really Building
The most important part of MTN’s fintech strategy may not be MoMo itself.
It is the combination of:
317 million telecom customers
70.8 million MoMo users
2.3 million merchants
1.4 million agents
13 billion fintech transactions
Those numbers give MTN something that many fintech startups spend years trying to build: distribution at scale.
The challenge is converting that distribution into deeper customer engagement.
If MTN can convince more of its telecom customers to become active MTN MoMo customers, the company could significantly expand the role of fintech within its broader business.
The TechBrass Take
MTN’s bigger fintech bet is not simply about building another mobile wallet.
It is about turning a telecom relationship into a financial relationship.
The company’s advantage is obvious: it already has hundreds of millions of customers across its markets.
The challenge is making MoMo useful enough for those customers to use it regularly.
Nigeria will be an important test because of its enormous market and fintech activity.
South Africa will provide a different test, where MTN must compete in a much more mature financial environment.
The Ant International partnership adds another dimension by giving MTN the technology to build a broader digital ecosystem around MoMo.
The opportunity is therefore much bigger than mobile money.
If MTN succeeds, the next generation of MTN MoMo customers may not think of MoMo simply as a way to send money.
They could use it to save, borrow, shop, receive money, pay businesses and manage more of their financial lives from one platform.
And that is ultimately what MTN is betting on:
317 million telecom relationships becoming millions more active fintech relationships.
OUTBOUND LINKS — FIXING YOUR YOAST WARNING
You need at least 2–3 useful external links in the article. Don’t add random links just to satisfy Yoast.
I recommend these:
1. MTN Fintech platform
Use the anchor:
MTN’s fintech platform
Place it in the section “MTN Wants More Than Mobile Money Customers.”
2. Ant International partnership
Use the anchor:
MTN’s partnership with Ant International
MTN’s strategic partnership with Ant International
Place it in “Why Ant International Matters.”
3. MTN subscriber figures
Use the anchor:
MTN’s latest subscriber and fintech figures
Place it in the opening or “The 317 Million Subscriber Opportunity” section.
These aren’t filler links; they give readers primary-source information directly from MTN.