
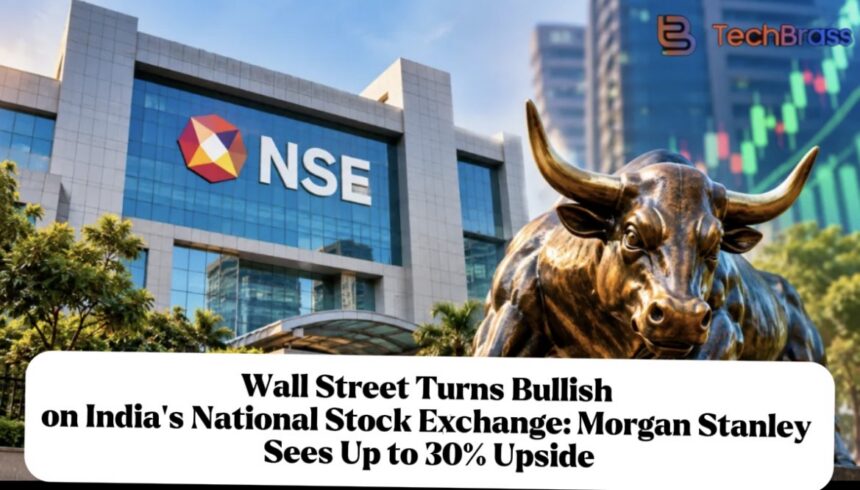
India’s biggest stock exchange has attracted a fresh wave of confidence from some of Wall Street’s most influential financial institutions.
Morgan Stanley and JPMorgan have initiated coverage of the National Stock Exchange of India (NSE) with bullish ratings, joining other brokerages that believe the exchange could benefit from India’s expanding investment market.
Morgan Stanley has set a 12-month price target of ₹2,315 per share, suggesting potential upside of around 30% from the previous Friday’s closing price. JPMorgan’s target is ₹2,130, while Indian brokerage 360 ONE has set a target of ₹2,100.
The interesting part? NSE shares have mostly traded below their September 2026 IPO price since listing.
So why are major investment firms becoming optimistic about the exchange, and what makes NSE such an important player in India’s financial system?
Why Are Wall Street Brokers Bullish on NSE?
The main attraction is NSE’s dominant position in India’s stock market.
The exchange operates one of the country’s most important financial-market infrastructures, connecting investors, brokers, listed companies and financial institutions.
Its scale gives it a significant advantage: when more investors trade on a particular exchange, liquidity tends to improve. Better liquidity can attract even more investors and trading activity, creating a cycle that is difficult for competitors to replicate.
Morgan Stanley described NSE as an important engine of India’s capital markets, highlighting its exposure to the growing movement of household savings into financial investments.
JPMorgan also sees the exchange benefiting from rising retail participation and the long-term expansion of India’s equity market.
In simple terms, these brokerages are not just betting on NSE’s current market dominance. They are betting that more Indians will invest in shares over the coming years — and that NSE will capture a large share of that activity.
Morgan Stanley’s ₹2,315 Target: Where Does the 30% Upside Come From?
Morgan Stanley has set a 12-month price target of ₹2,315 for NSE shares.
The brokerage believes the exchange could benefit from several long-term trends:
More retail investors: A growing number of Indians are entering the stock market.
Increasing financialisation: More household savings are moving into shares and other financial products.
Strong market position: NSE remains the dominant exchange in several major trading segments.
Scalable technology: Its infrastructure can support higher trading volumes without costs necessarily rising at the same pace.
Morgan Stanley also expects NSE’s revenue and normalised profit after tax to grow at approximately 15% annually between fiscal years 2027 and 2029.
One figure from its research stands out: only around 3.2% of India’s working-age population participates in NSE’s cash-equity market, while approximately 0.7% participates in equity derivatives.
That suggests significant room for broader participation — although greater participation is not guaranteed, and growth will depend on economic conditions, investor confidence and regulation.
JPMorgan Also Sees More Room for Growth
JPMorgan has initiated coverage with an Overweight rating and a price target of ₹2,130.
Its investment case is built around NSE’s market leadership, increasing retail participation and the potential for stronger earnings.
The brokerage expects adjusted profit after tax to grow at a compound annual growth rate of approximately 14% between FY27 and FY29.
It also believes the exchange’s profitability could remain strong, with projected EBITDA margins improving from 75.3% in FY27 to 77.1% in FY29.
But JPMorgan is watching one important issue: NSE’s share of the equity-options market has declined as competition has increased.
Its view is that the worst of this market-share erosion may be behind the exchange, with signs of stabilisation emerging.
That matters because options trading has been a major source of NSE’s revenue.
NSE’s Biggest Advantage: Its Market Dominance
To understand the bullish forecasts, it helps to look at how much of India’s trading activity passes through NSE.
According to figures cited by brokerages, NSE held approximately:
These figures illustrate the exchange’s scale, particularly in cash equities and futures.
However, the index-options figure deserves attention. NSE’s share in this segment has fallen from much higher levels as competitors, especially the Bombay Stock Exchange (BSE), have gained ground.
That is why analysts are looking beyond market share alone. They are also examining how NSE can grow revenue from technology, data, commodities and other services.
NSE Wants to Grow Beyond Options Trading
This could be one of the most important parts of its long-term growth story.
For years, trading activity — particularly equity derivatives — has played a major role in NSE’s revenue generation.
But relying heavily on one business segment creates risk. Regulatory changes, lower trading volumes or stronger competition could affect earnings.
NSE is therefore looking to develop other revenue streams, including:
Commodity derivatives: Expanding trading opportunities beyond traditional equities.
Electronic gold receipts: Supporting digital trading and ownership records linked to physical gold.
Market data and technology: Generating revenue from data, analytics and financial-market infrastructure.
Jefferies estimates that newer businesses such as commodities, mutual-fund ordering and electronic gold receipts could contribute an additional 15% to revenue and profit by fiscal 2030.
That is a forecast, not guaranteed growth. But it shows why analysts believe NSE could become more than just a place where investors buy and sell shares.
What About Competition From the Bombay Stock Exchange?
Bombay Stock Exchange (BSE)
India’s other major stock exchange and an increasingly important competitor in equity derivatives.
NSE’s dominance does not mean it has no competition.
BSE has been growing its presence in derivatives, particularly in segments where NSE previously enjoyed a much larger share.
This competition matters because brokers can route orders to different exchanges, and investors may choose platforms based on liquidity, pricing and execution quality.
Still, NSE retains a substantial advantage in trading volumes, market infrastructure and liquidity.
Macquarie, which initiated coverage with an Outperform rating, has also highlighted NSE’s scale and expects revenue to grow at around 12% annually between FY26 and FY30.
The brokerage nevertheless expects some market-share pressure from BSE over the coming years.
The Risks Investors Should Not Ignore
Despite the bullish forecasts, NSE is not a risk-free investment.
There are several challenges investors should monitor.
1. Regulatory changes
India’s market regulator can introduce rules that affect derivatives trading, transaction charges and market participation. Stricter rules could reduce trading activity and affect NSE’s revenue.
2. Competition from BSE
If BSE continues gaining market share, NSE could face pressure in some of its most profitable business segments.
3. Dependence on derivatives
A large portion of NSE’s operating revenue comes from transaction charges, particularly options trading. This concentration makes the exchange vulnerable to changes in trading behaviour and regulation.
4. Valuation concerns
A dominant market position does not automatically make a stock cheap. Investors must consider the price they are paying relative to future earnings and growth expectations.
5. Technology and operational risks
Stock exchanges depend on reliable technology infrastructure. Major outages, cyberattacks or disruptions could damage investor confidence and affect trading activity.
These risks explain why bullish price targets should be treated as analyst expectations rather than promises of future returns.
Why Is NSE Trading Below Its IPO Price?
There is an interesting contrast in this story.
NSE completed its long-awaited stock market listing in September 2026 at an IPO price of ₹1,785 per share. Its shares made a relatively modest debut, listing at around ₹1,800.
Although the stock subsequently recorded gains, it has mostly traded below its IPO price during the period discussed in the latest analyst coverage.
This creates an interesting situation: some major brokerages are now recommending the stock even though its market performance has not consistently matched the optimism surrounding its listing.
Morgan Stanley’s ₹2,315 target and JPMorgan’s ₹2,130 target suggest that these firms believe the market may be undervaluing NSE’s longer-term earnings potential.
However, investors should remember that analyst targets can change as new financial results, regulations and market conditions emerge.
What This Means for India’s Financial Markets
The growing interest in NSE reflects a much bigger trend: India’s capital markets are becoming increasingly important to global investors.
As more people participate in investing, companies raise capital and financial products expand, the infrastructure supporting those activities becomes more valuable.
NSE sits at the centre of much of that activity.
Its future growth could benefit from:
More Indians investing in equities.
Greater participation from institutional investors.
Growth in mutual funds and exchange-traded funds.
Expansion of commodities and other financial products.
Increasing demand for market data and technology services.
For international investors, NSE offers exposure to the expansion of India’s financial system through a business that already has a strong competitive position.
The challenge will be turning that opportunity into sustainable earnings growth while navigating regulation and competition.
Frequently Asked Questions
1. Why are Wall Street analysts bullish on NSE?
Morgan Stanley and JPMorgan believe NSE can benefit from its dominant market position, rising retail investment participation and the long-term expansion of India’s capital markets.
2. What is Morgan Stanley’s NSE share price target?
Morgan Stanley has set a 12-month target of ₹2,315 per share, implying approximately 30% upside from the reference closing price used in its November 2 report.
3. What is JPMorgan’s target for NSE?
JPMorgan has set a price target of ₹2,130 per share and initiated coverage with an Overweight rating.
4. Does NSE control India’s entire stock market?
No. NSE is the dominant exchange in several segments, but it competes with other exchanges, particularly BSE.
5. What are NSE’s biggest risks?
Key risks include regulatory changes, competition from BSE, declining derivatives market share, dependence on options revenue and technology disruptions.
6. Is NSE a good stock to buy?
Analysts have expressed positive views about its long-term prospects, but that does not guarantee returns. Investors should consider its valuation, financial performance, risks and their own investment objectives.
Final Thoughts: Wall Street Is Betting on India’s Investment Boom
The growing optimism around NSE is about more than one stock exchange.
Morgan Stanley, JPMorgan and other brokerages are effectively betting that India’s financial markets have significant room to grow — and that NSE is well-positioned to benefit.
Its market dominance, strong margins, technology infrastructure and potential new revenue streams make it an interesting business to watch.
But the exchange also faces real challenges, particularly from regulatory changes and BSE’s growing competition.
The big question is whether NSE can maintain its dominance while finding new ways to grow beyond derivatives trading.
What do you think? Is NSE positioned to become an even bigger force in global financial markets, or are investors underestimating the risks?
Share your thoughts in the comments.