
African fintech companies are no longer satisfied with simply helping people send and receive money. Increasingly, they want to hold deposits, provide loans, manage customers’ money and control more of the financial infrastructure behind their services.
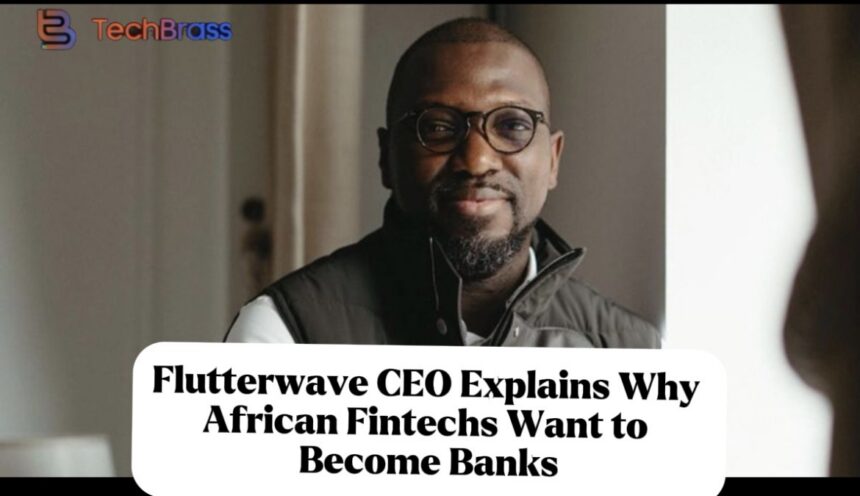
Flutterwave CEO Olugbenga “GB” Agboola says the shift is about gaining greater control over the customer experience and reducing dependence on traditional banks.
Speaking at the Moonshot by TechCabal conference in Lagos on October 28, 2026, Agboola explained why Flutterwave is expanding beyond payment processing into banking, lending and other financial services.
His comments reflect a wider change across Nigeria’s fintech industry, where companies that once competed with banks are now seeking banking licences and building closer relationships with the financial system.
The big question is: why do fintech companies want to become the very institutions they once set out to disrupt?
Why Flutterwave Wants to Become a Bank
Flutterwave built its reputation by helping businesses accept payments from customers across Africa and international markets.
But according to Agboola, processing payments is only one part of what businesses need.
A company that receives money through Flutterwave may also need to store its earnings, pay suppliers, access working capital, make international transfers and invest surplus funds.
Flutterwave wants to bring more of these services together on one platform.
Agboola explained the logic with a simple observation:
“If you can trust us with your payment, it’s a much easier sell to actually keep the money for you.”
In other words, once customers trust a fintech to process their transactions, the company has an opportunity to offer additional financial services.
This is not simply about adding more features to an app. It is about building a deeper relationship with customers and becoming part of more stages of their financial activities.
The Problem With Depending on Traditional Banks
One of the biggest reasons Flutterwave wants to move into banking is its reliance on third-party financial institutions.
For years, fintech companies have depended on commercial banks to provide essential services such as holding customer funds, processing settlements and connecting to banking networks.
That arrangement works, but it creates a problem: a fintech cannot always control the reliability of services provided by another institution.
Agboola explained that when a partner bank experiences downtime or schedules system maintenance, services that depend on that bank can also be disrupted.
For a business processing thousands of transactions, even a short interruption can create serious problems.
He argued that fintech companies need to control more of the infrastructure behind their services to deliver a more reliable customer experience.
As he put it, companies cannot consistently provide an excellent payment experience if they do not control the entire infrastructure, or at least a significant part of it.
However, Flutterwave is not abandoning partnerships with traditional banks. The company intends to continue working with financial institutions while taking direct control of the parts of its operations it considers essential.
Flutterwave’s Banking Licence Changes Its Business Model
Founded in 2016 | Co-founder and CEO: Olugbenga Agboola
Flutterwave’s banking ambitions are not just future plans. The company secured a Nigerian national microfinance banking licence in April 2026.
The licence followed its acquisition of open-banking startup Mono earlier in the year.
This is a significant development because it allows Flutterwave to hold customer deposits and provide lending services within the regulatory limits of its licence.
Previously, its payments business relied on partner banks for important parts of these financial services.
The new licence gives Flutterwave greater control over how funds move through its ecosystem and creates opportunities to expand into banking products.
It is important to understand that this is a microfinance banking licence, not a full commercial banking licence. Flutterwave’s banking activities remain subject to the rules and limits attached to that regulatory category.
From Processing Payments to Offering Loans
Perhaps the most interesting opportunity is lending.
Flutterwave already processes payments for businesses and can observe important aspects of their financial activities.
For example, its infrastructure may provide information about:
How frequently a business receives payments.
The volume of transactions it processes.
How much money moves through its accounts.
Whether customers regularly make payments.
When a business might need additional working capital.
This information could help Flutterwave assess the financial activity of businesses seeking credit.
Imagine a fashion retailer in Lagos that receives payments through Flutterwave every day.
The retailer may have consistent sales but still struggle to pay suppliers before the next batch of customer payments arrives.
With access to appropriate transaction data, a lending business could better understand the retailer’s cash flow and assess whether short-term financing makes sense.
Agboola indicated that Flutterwave’s initial lending ambitions are focused more on liquidity and working-capital infrastructure than immediately becoming a mass-market consumer lender.
One example is helping businesses pre-fund payouts when they need to send money before receiving their own funds.
This could become an important additional revenue stream for the company.
Why Other African Fintechs Are Following the Same Direction
Flutterwave is not alone in this transition.
Across Nigeria, several fintech companies are moving beyond payment processing into regulated banking.
Paystack acquired Ladder Microfinance Bank in January 2026 and launched Paystack Microfinance Bank as a separate regulated entity. Its initial plans include lending to businesses and offering banking-as-a-service products.
Moniepoint has expanded its regulated banking operations and received national microfinance bank licence status in Nigeria. It has also expanded beyond Nigeria through its acquisition of a majority stake in Kenya’s Sumac Microfinance Bank.
Sycamore’s founder, Babatunde Akin-Moses, has also discussed the industry’s shift towards owning more financial infrastructure and becoming regulated financial institutions.
The pattern is becoming clearer.
Fintechs initially built businesses around one major service: payments, lending, savings or transfers.
Now, many want to combine several financial services under a broader business structure.
The competition is no longer just about who has the best payment app. It is increasingly about who controls the financial infrastructure customers rely on.
What This Means for Traditional Banks
The expansion of fintechs into banking could intensify competition for Nigeria’s established commercial banks.
Traditional banks have historically controlled much of the infrastructure used to hold deposits, provide credit and settle financial transactions.
But fintechs have built strong relationships with customers through convenient digital products and business-focused payment services.
If these companies can now hold deposits and lend directly, they could compete for some of the same customers and revenue streams.
For example, a small business that previously used a fintech only to collect payments could eventually use the same platform to:
Receive customer payments.
Keep its business funds.
Pay suppliers.
Access working-capital loans.
Make domestic and international transfers.
Invest surplus cash through available financial products.
That creates a more complete financial relationship.
Still, traditional banks are not going away. They have established deposit bases, regulatory experience, large balance sheets and extensive infrastructure.
The more likely outcome is increased competition alongside continued partnerships between banks and fintech companies.
The Stablecoin Opportunity: Another Part of Flutterwave’s Expansion
Flutterwave’s ambitions also extend beyond conventional banking.
The company has been developing stablecoin-powered payment and settlement infrastructure to make cross-border transactions easier.
In June 2026, Flutterwave announced a Series E funding round at a reported valuation of $3.25 billion, alongside a partnership with Ripple that integrated its RLUSD stablecoin into its payment infrastructure.
It has also worked on stablecoin balances and embedded wallets supporting USDC and USDT.
These developments point towards a broader strategy: enabling businesses to move, store and manage money through connected financial services, rather than relying on a single payment product.
For African businesses dealing with international suppliers, cross-border settlement can be complicated by currency conversion, liquidity constraints and delays.
Stablecoins could offer another settlement option, although their use remains subject to applicable regulations, liquidity and operational risks.
The Risks: Becoming a Bank Is Not as Easy as Building an App
There is a reason banking is one of the most heavily regulated industries.
A fintech can build an attractive application and attract millions of users, but managing deposits and lending money introduces a different level of responsibility.
Some of the major challenges include:
1. Regulatory compliance
Licensed financial institutions must meet capital, reporting, governance and consumer-protection requirements. Operating across multiple African countries makes compliance even more complicated.
2. Credit risk
Lending creates the possibility that borrowers will fail to repay. Transaction data can improve credit assessments, but it cannot eliminate default risk.
3. Customer trust
Holding customer deposits requires a high level of security, transparency and operational reliability. A payment platform must earn additional trust when it becomes responsible for customers’ money.
4. Cybersecurity
As fintechs manage more financial activities, they become increasingly attractive targets for cybercriminals. Protecting accounts, transaction systems and customer information becomes even more important.
5. Competition
Flutterwave and other fintechs will face competition not only from traditional banks but also from established digital banks and other licensed financial institutions.
The companies that succeed will need more than popular apps. They will need strong risk management, reliable infrastructure and the ability to operate sustainably under financial regulation.
Frequently Asked Questions
1. Why does Flutterwave want to become a bank?
Flutterwave wants greater control over its financial infrastructure, reduce dependence on partner banks and expand beyond payments into deposits, lending and other financial services.
2. Who is the CEO of Flutterwave?
Olugbenga “GB” Agboola is the co-founder and chief executive officer of Flutterwave.
3. Does Flutterwave have a banking licence in Nigeria?
Yes. Flutterwave secured a national microfinance banking licence in April 2026, allowing it to hold deposits and provide lending services within the licence’s regulatory limits.
4. Is Flutterwave becoming a full commercial bank?
Not based on the licence announced in April 2026. It secured a microfinance banking licence, which is different from a full commercial banking licence.
5. Which other Nigerian fintechs are moving into banking?
Paystack and Moniepoint are notable examples. Paystack acquired Ladder Microfinance Bank in January 2026, while Moniepoint has expanded its microfinance banking operations.
6. Will fintechs replace traditional banks?
Not necessarily. Fintechs may compete with banks in deposits, payments and lending, but partnerships will remain important because financial institutions still depend on one another for infrastructure, liquidity and settlement services.
Final Thoughts: African Fintech Is Entering a New Phase
For years, African fintech companies focused on making financial services faster, cheaper and easier to access.
Now, they want to control more of the systems behind those services.
Flutterwave’s move into microfinance banking reflects that changing ambition. It wants to do more than help businesses receive money. It wants to become part of how they store, manage, borrow and move that money.
And with Paystack, Moniepoint and other players pursuing similar strategies, the competition across Africa’s financial services industry could become even more intense.
The next big African fintech company may not simply be the one that processes the most payments. It could be the one that builds the financial infrastructure businesses depend on every day.
Do you think fintech companies like Flutterwave can build better banking experiences than traditional banks, or will they eventually face the same challenges?
Share your thoughts in the comments.